8 Best Business Credit Cards for Restaurants in 2026 (Powered By Real Data)
Author: Dylan Buckley
October 08, 2026
13 min read
TABLE OF CONTENTS
- 1. Best Business Credit Cards for Restaurants Compared
- 2. Why Flat Rate Cards Beat Category-Spend Cards for Restaurant Business Owners
- 3. Wells Fargo Signify Business Cash: Best Rewards for Restaurants
- 4. FairFigure Lift Card: Best for Bad Credit/Building Business Credit
- 5. American Express Blue Business Cash: Best Amex for Cash Rewards
- 6. American Express Business Gold: Best for Restaurant Owners Whose Dining Out and Shipping Spend Is High
- 7. U.S. Bank Triple Cash: Best for Restaurants with High Office Supply, Dining Out, and Phone Costs
- 8. Chase Ink Unlimited: Strong Cash-Back Card
Start your credit building journey for your business
We’ve conducted one of the most in-depth business credit card studies available online that we know of so far.
To provide you with data-driven insights, we looked at restaurants in the industry “Eating and Drinking” places, with a total spend of $2.7 million. We analyzed industry spend percentages and compared the category rewards of all of the major branded credit cards on the market.
Here’s what we found.
Best Business Credit Cards for Restaurants Compared
- Wells Fargo Signify Business Cash
- FairFigure Lift Card
- American Express Blue Business Cash
- American Express Business Gold
- U.S. Bank Triple Cash
- Chase Ink Unlimited
- Costco Anywhere Business
- Sam's Club Business
| Card | Perks | Fees/Interest | Best For… |
|---|---|---|---|
| Wells Fargo Signify Business Cash | 2% unlimited cash back with no annual fee. | No annual fee, 16.99% to 24.99% variable APR. | Best overall for restaurants. |
| FairFigure Lift Card | Revenue-based, EIN-only card. | Flat fee, no APR. | Those with bad credit or those who want to build business credit. |
| American Express Blue Business Cash | 2% cash back up to $50,000, 1% cash back thereafter. | No annual fee, 16.99% to 28.74% variable APR. | Cash rewards in the Amex ecosystem. |
| American Express Business Gold | 4x points on top two spending categories up to $150,000 per year (1x points after). | $375 annual fee, 17.99% to 28.74% APR if you pay over time. | High dining out and shipping spend. |
| U.S. Bank Triple Cash | 3% cash back on select categories, 1% unlimited cash back otherwise. | No annual fee, 17.49% to 26.49% variable APR. | High office supply, dining, and phone service spend. |
| Chase Ink Unlimited | Unlimited 1.5% cash back. | No annual fee, 16.74% to 24.74% variable APR. | Chase customers who want a good cash-back card. |
| Costco Anywhere Business | 2% cash back on all Costco and Costco website purchases. | No annual fee with active Costco membership, 18.99% to 26.99% variable APR. | Cash back on Costco wholesale supplies. |
| Sam's Club Business | 3% back in Sam's Cash on Sam's Club purchases for Plus members. | No annual fee, variable APR of 20.15% or 28.15%. | Cash back on Sam's Club/Walmart wholesale supplies. |
Why Flat Rate Cards Beat Category-Spend Cards for Restaurant Business Owners
According to our data, restaurants collectively spend around $2.7 million within just a few months.
If we look at our internal spend data, we find that around 47% of spend is on food and dining purchases. Nearly half of business expenses go to “food and dining.”
As a restaurant business owner, this makes any category-spend cards with high cash back rewards for food and dining sound like an obvious choice. After all, if you spend the majority of your money on food and dining, this makes sense, right?
While restaurants are spending money on food, the bulk of their spending is actually going toward wholesale supply. Because it’s coded as such, you aren’t actually getting any cash back if you use a business credit card with high rewards for dining.
Looking at the numbers, here’s how much cash back restaurant business owners are earning via category-spend business credit cards.
- Amex Business Gold Card: 1.62%.
- Chase Ink Cash: 1.48%.
- U.S. Bank Triple Cash: 1.42%.
A flat-rate business credit card with an effective rate of 2% is going to earn your business far more rewards over time.
With all that in mind, which business credit cards are going to be the right fit for your restaurant?
Best Business Credit Cards for Restaurants Compared
1. Wells Fargo Signify Business Cash: Best Rewards for Restaurants
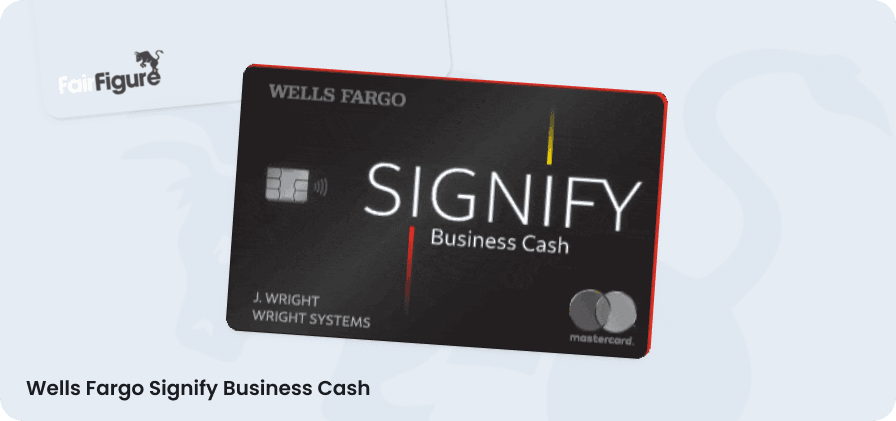
The Wells Fargo Signify Business Cash card stands out as the best business credit card for restaurant owners.
It’s a flat-rate cash back card offering 2% unlimited cash back on all purchases. Unlike other cards, every single purchase is going to help you save money and stack up rewards.
For example, if you’re spending $15,000 per month, you’re getting around $3,600 back per year in rewards.
With this business credit card, you get:
- 0% introductory APR for 12 months. After that, 16.99% to 24.99% variable APR.
- $0 annual fee.
- A $500 cash rewards bonus when you spend at least $5,000 within three months of account opening.
- Employee cards at no additional cost to you with card membership.
It’s a great choice if you want a card without limits or spending categories that you can use to maximize your cash back rewards.
2. FairFigure Lift Card: Best for Bad Credit/Building Business Credit
Is bad credit holding your business back from the funding you need to scale? If you’re generating revenue, you can turn to a revenue-based business card instead, such as the FairFigure Lift Card.
The FairFigure Lift Card is an EIN-only business card that requires no personal credit check, no personal guarantee, and no paperwork. All you need to get a card for your business is at least three months in business and $2,500 in monthly revenue.
As you grow your restaurant, your spending limit will grow as well. The more you make, the more funding you have to tap into, increasing your cash flow for your small business.
If you’re looking for business credit cards with no personal credit check, consider this EIN only business credit card alternative.
Unlike other business cards, you have some flexibility with your payback terms. You can choose between four-week and eight-week payback terms.
Beyond funding, your FairFigure Lift Card helps you build credit.
Your FairFigure Lift Card is reported as a tradeline. Every card payment is reported to the SBFE, Equifax, Experian, Dun & Bradstreet, and Creditsafe to build your credit scores.
3. American Express Blue Business Cash: Best Amex for Cash Rewards
Some restaurant business owners want to stick with card options offered by the institution they bank with. If you’re with American Express, you might want the American Express Blue Business Cash Card.
The American Express Blue Business Cash Card offers 2% cash back. However, there are limitations.
You only get 2% cash back on $50,000 of eligible purchases per calendar year. After you reach this threshold, your rewards drop to 1% cash back on all purchases thereafter.
The Amex Blue Business Cash business credit card comes with:
- 0% introductory APR for the first 12 months. After that, you’re looking at a variable APR of 16.99% to 28.74%.
- A $250 statement credit if you spend at least $3,000 within three months of getting your card.
- Pre-approval to see if you qualify without affecting your personal credit.
- No annual fee with this business credit card.
- Expanded Buying Power to go beyond your credit limit when you need it.
Check out our other credit card industry articles here: Business Credit Cards for Sole Proprietors, Law Firms, Construction, Ecommerce, Consultants, Real Estate Agents, and Retail Stores.
4. American Express Business Gold: Best for Restaurant Owners Whose Dining Out and Shipping Spend Is High
Flat-rate cards are generally better than category-spend cards. However, there are always exceptions, especially when it makes sense for your business. The Amex Business Gold Card is perfect if you regularly dine out or you spend a lot on shipping.
The American Express Business Gold Card is a charge card that offers 4x points on your top two spending categories up to $150,000 each calendar year. This is more in line with startup business credit cards with no credit EIN only than traditional credit cards.
These categories include:
- Advertising for select media.
- Purchases made at electronic goods retailers.
- Purchases made at software and cloud systems providers.
- Restaurant purchases, including takeout and delivery.
- Purchases made at gas stations.
- Transit purchases.
- Monthly wireless telephone service charges.
Once you reach the limit, you’ll earn 1x points on every eligible purchase until next calendar year. This card also offers 3x points on prepaid hotels and flights booked through AmexTravel.com.
You can also expect:
- Up to 200,000 in membership rewards points after you spend $15,000 in eligible purchases within three months of account opening.
- An annual fee of $375.
- Additional credits with business partners you use or plan on using. This includes FedEx, Walmart+, and more.
- No preset spending limit, which can bolster your cash flow.
- Ability to pay for purchases over time. If you choose the Pay Over Time option, you can expect 17.99% to 28.74% APR.
Employee cards will cost you. You’re looking at $95 for the first five cards. Then, $95 for each Card after, with a limit of 99 employee cards.
It’s worth it if you redeem Membership Rewards for travel at 1.5¢+. Using travel rewards will see you receive an average of around 2.0% to 2.4% cash back, which is enough to clear the $375 fee.
5. U.S. Bank Triple Cash: Best for Restaurants with High Office Supply, Dining Out, and Phone Costs
Another great example of a category-spend card that can benefit businesses with specific business expenses is the U.S. Bank Triple Cash business credit card.
Aptly named, the U.S. Bank Triple Cash card offers 3% cash back on spending with cell phone service providers, office supply stores, restaurants, and gas and EV charging stations (only for transactions of $200 or less).
It’s important to note the fine print on the last spending category. More than that, they exclude discount stores and wholesale clubs.
For all other eligible purchases, you’ll earn unlimited 1% cash back.
Some other benefits of this business credit card include:
- A $100 annual statement credit for software service purchases. This statement credit applies to purchases at FreshBooks or QuickBooks, for example.
- Introductory 0% APR for 12 months. After that, 17.49% to 26.49% variable APR.
- No annual fee.
- 5% cash back on prepaid hotels and car rentals booked through the Travel Center.
- ExtendPay Plans for your small business ($0 fee-free for the first 60 days after account opening).
6. Chase Ink Unlimited: Strong Cash-Back Card
Chase Ink Unlimited is a solid cash-back card with ample ways to claim your rewards.
The rewards start with unlimited 1.5% cash back on all purchases. Beyond that, you can bolster your rewards with:
- 5% cash back on Lyft rides through September 30, 2027.
- A complimentary three-month Instacart+ membership, available until December 31, 2027.
- $750 cash back if you spend at least $6,000 in the first three months after getting your new card.
- Referrals, which can earn you up to 200,000 points per year. You get 40,000 bonus points per successful referral that gets approved for a Chase for Business card.
The Chase Ink Unlimited credit card comes with 0% introductory APR for the first 12 months. Then, you can expect 16.74% to 24.74% variable APR after that. This is a bit lower than other business credit cards on this list.
It has no annual fee.
Unlike other business credit cards, you can use your cash back to get actual cash, gift cards, travel, and more.
7. Costco Anywhere Business: Great for Wholesale Supplies
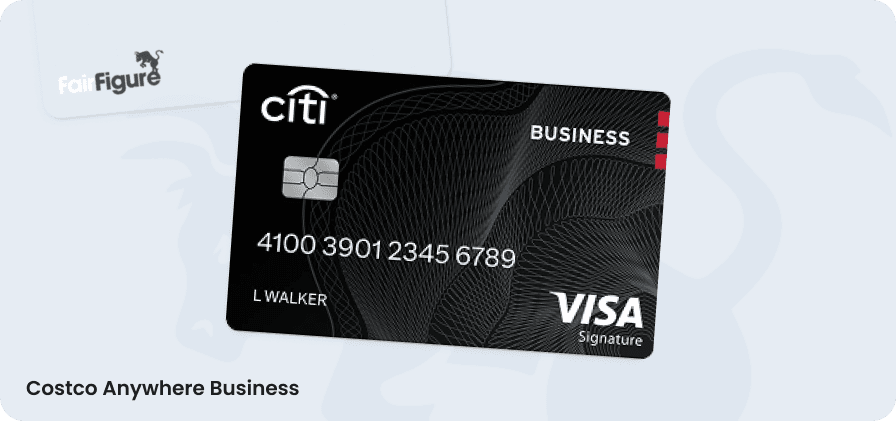
Business credit cards from traditional institutions aren’t your only options as a restaurant owner. Since you rely on wholesale goods to keep your restaurant running, why not consider a card from places where you primarily do business, such as the Costco Anywhere Business Card?
The Costco Anywhere Business Card is powered by the card issuer, Citi. There’s a $0 annual fee if you have an active Costco membership. A Costco membership is required for card membership. There’s also no authorized user fee.
Costco offers different rewards for different categories of business expenses. Here’s the breakdown for this business credit card if you’re a card member:
- 5% cash back on gas at Costco.
- 4% cash back on other eligible gas and EV charging.
- 3% cash back on restaurants and eligible travel.
- 2% cash back on all other Costco and Costco.com purchases.
- 1% cash back on all other purchases.
It’s important to note that the first two categories do come with restrictions. You only get 5% or 4% cash back up to $7,000 in a calendar year. After that, it drops to 1% cash back.
There’s no limit to how much you can earn in rewards. However, you’ll only see your cash back as an annual credit card reward certificate after your February billing statement closes. It’s not the best credit card if you want flexible access to your rewards.
Interest on this business credit card is average. You can expect a 18.99% to 26.99% variable APR depending on creditworthiness. They unfortunately don’t have an introductory APR promo that other cards offer.
8. Sam's Club Business: Great for Wholesale Supplies
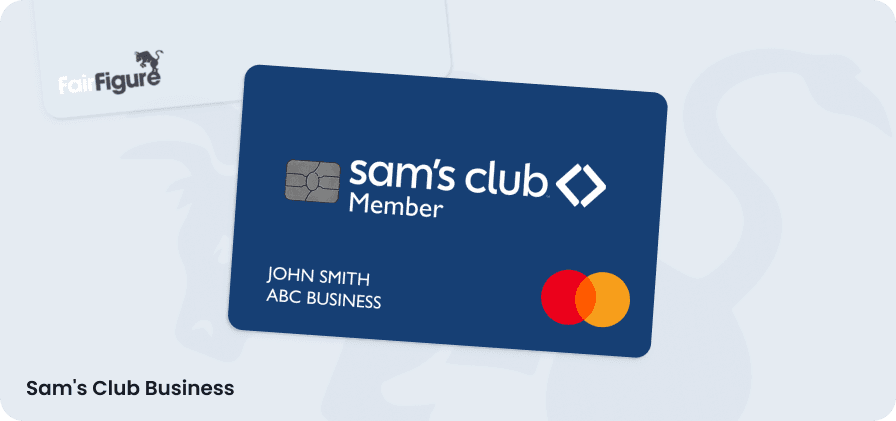
If you shop primarily at Sam’s Club instead of Costco (or you shop at both), another business credit card option is the Sam’s Club Business Mastercard.
The Sam’s Club Business Mastercard is the one to spring for. Their regular member card isn’t going to earn you rewards. Make sure you’re not signing up for the personal credit card. Business credit cards are available through Synchrony.
The Sam’s Club Business Mastercard will get you:
- 5% back in Sam’s Cash on gas anywhere that Mastercard is accepted. (This is only up to $6,000 per year. Then, 1% after.)
- 3% back in Sam’s Cash on Sam’s Club purchases for Plus members. If you’re just a regular member with card membership, you’re only going to get 1% back.
- 3% back in Sam’s Cash on dining and takeout.
- 1% back in Sam’s Cash on other purchases.
The Sam’s Club Business Mastercard comes with no annual fee or foreign transaction fees. It’s accepted at Sam’s Club and Walmart locations nationwide, and it doubles as your membership card so that you don’t have to carry both around.
It comes with a variable APR of 20.15% or 28.15%.
The major downside of these business credit cards? Business owners can only earn a maximum of $5,000 in Sam’s Cash in a calendar year. Combined purchases from employee cards contribute to this limit.
Methodology
We used internal data from 5,769 customers, 75 industries, and 506,801 transactions from May 30, 2026, to August 25, 2026, to calculate total spend and spend percentages.
More articles
Read More >
October 08, 2026
15 min read
October 08, 2026
12 min read
October 08, 2026
13 min read
Start your credit building journey for your business
Start your credit journey now with FairFigure